Make room for island life
Beaches, mountain towns, Old San Juan and a warm climate offer very different ways to make Puerto Rico home. Spanish and English are official languages; Spanish is more commonly spoken.
PUERTO RICO RESIDENCY & ACT 60
Keep your U.S. citizenship. Qualifying Puerto Rico-source income can be exempt from U.S. federal income tax. For Americans who become bona fide residents, Puerto Rico offers a distinctive route to federal tax relief while living in a U.S. territory. See the IRS rules.
Different individual and business tax bases. Your total tax depends on eligibility, income sources, salary and other applicable taxes.
The 4% business rate requires an approved Act 60 export-services decree and qualifying Puerto Rico operations. Federal residency and income-sourcing rules apply separately. ExitGlobal helps you prepare your move and identify the advice you need.
No payment. No account needed to start. Save when you choose.
Explore the benefits and rules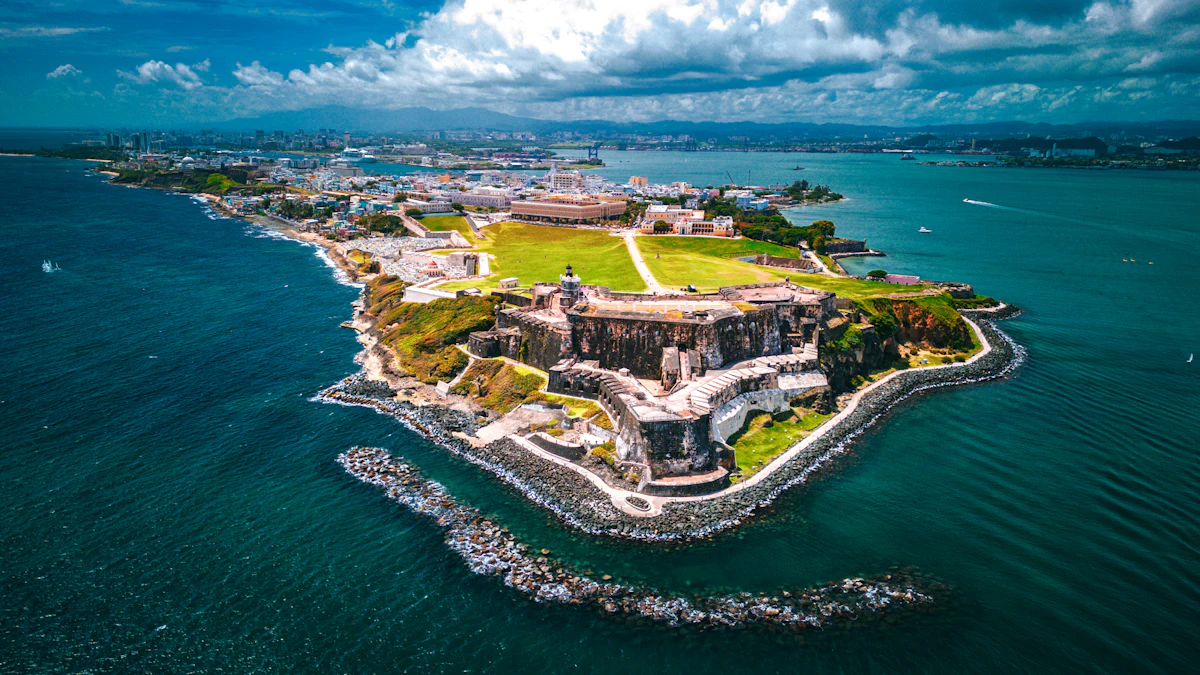
A new life.
A clearer direction.
THE OPPORTUNITY
Puerto Rico combines island living with the U.S. dollar, connections to the mainland and a distinct tax system. The right move starts with understanding both the opportunity and the commitment.
Beaches, mountain towns, Old San Juan and a warm climate offer very different ways to make Puerto Rico home. Spanish and English are official languages; Spanish is more commonly spoken.
Puerto Rico is a U.S. territory and uses the U.S. dollar. U.S. citizens can relocate without a new immigration visa or giving up citizenship. Non-U.S. citizens need an appropriate U.S. immigration status; Act 60 does not grant one.
Approved Act 60 incentives can reduce Puerto Rico tax on qualifying business or investment income. Separately, bona fide residents may generally exclude Puerto Rico-source income from U.S. federal income tax, subject to federal rules.
ACT 60, EXPLAINED
Act 60 is Puerto Rico’s Incentives Code. A tax exemption decree is the government’s approval of specific benefits and obligations. There are separate routes for an export business and a resident individual investor; some people apply for both.
EXPORT SERVICES · FORMERLY ACT 20
An eligible business operating from Puerto Rico and serving customers outside Puerto Rico can generally obtain a 4% Puerto Rico income tax rate on eligible net income under an approved export-services decree.
Qualifying activities can include consulting, software and other professional services. The service, customer location, Puerto Rico operations and decree conditions all matter. An LLC or a remote job alone does not qualify.
Salary, payroll, nonqualifying income, distributions and U.S. owner obligations need their own analysis. The business rate is not a blanket personal tax rate.
RESIDENT INDIVIDUAL INVESTOR · FORMERLY ACT 22
This separate decree covers eligible interest, dividends and capital gains after establishing Puerto Rico residence. It requires qualifying residency history and ongoing compliance.
Law 38-2026, signed March 10, 2026, changes the rules for applications filed from January 1, 2027. The application date matters, along with eligibility and the approved decree.
U.S.-source dividends and interest can remain federally taxable. Gains built up before your move require a separate calculation; moving does not erase the tax on earlier appreciation.
| Rule | Filed by December 31, 2026 | Filed from January 1, 2027 |
|---|---|---|
| Eligible interest, dividends & post-move appreciation | Generally 0% Puerto Rico tax under the existing exemption framework. | Generally 4% Puerto Rico tax, unless a more favorable statutory rate applies. |
| Benefit horizon | Existing framework through December 31, 2035. | New framework through December 31, 2055. |
| Prior Puerto Rico residence | Existing eligibility includes no Puerto Rico residency between January 17, 2006 and January 17, 2012. | The amended definition retains the historical exclusion and adds at least six years of nonresidency before moving. Have the full residence history assessed. |
Already have a decree? Law 38 preserves existing rights and obligations. Existing holders can request a modification to the new framework; pending applications filed by the 2026 cutoff can elect it. Earlier decrees do not automatically switch to 4% in 2027 or automatically extend to 2055.
Read the complete program guide → Origins in 2012, the 2019 consolidation, donation changes, home ownership, annual costs and worked income examples.
Sources: Law 38-2026, enacted text (Spanish) · Act 60, Chapter 3 (export services) · IRS income sourcing rules
BECOMING A BONA FIDE RESIDENT
Federal bona fide residence generally requires all three tests below. Receiving an Act 60 decree does not, by itself, establish IRS residency.
The common route is at least 183 days in Puerto Rico during the tax year. Other qualifying presence tests and exceptions exist. Keep a travel log and supporting records.
Generally, you must not have a tax home outside Puerto Rico. Your main place of business or work matters; renting an apartment while your work remains based elsewhere may not meet this test.
You must not have a closer connection to the mainland U.S. or another country. Home, family, belongings, business and social ties, banking and official records help establish the facts.
Plan the year of your move. Special transition rules can apply. Your federal status, Puerto Rico residency and departure from your former state or country must be assessed together. IRS Publication 570 explains all three tests and the move-year rules.
LIVING HERE & KEEPING YOUR DECREE
These home and donation requirements apply to the Act 60 resident individual investor route. They are separate from the federal residency tests and the export-business incentive.
2 years
Yes: the investor rules generally require you to purchase a home in Puerto Rico within two years after obtaining the decree, from an unrelated seller, and use it as your principal residence.
Maintain a qualifying owned principal residence during the decree and provide annual evidence. You can initially rent, but renting alone does not satisfy this purchase requirement. A holiday home that you do not actually live in is insufficient.
For applications filed from January 1, 2027, title must be registered or pending registration in your name, jointly with your spouse, or in a qualifying statutory trust. Earlier applications have different administrative options; confirm the ownership structure before buying through an entity.
$10,000+
Act 60 resident individual investors generally must contribute at least US$10,000 each year. Under the current allocation:
Eligible recipients must satisfy the applicable independence rules. Keep receipts and the Fund’s contribution certificate for annual reporting.
2026 update: DDEC Circular 2026-001 requires evidence of the Fund contribution beginning in 2026. Older Act 22 decrees may have different obligations; check your decree.
The investor annual-report fee is US$5,000, separate from the donation. That means a typical Act 60 investor should budget at least US$15,000 per year for those two items alone, plus housing, professional fees, applicable taxes and other compliance costs.
File required Puerto Rico returns and compliance reports, maintain your residency evidence and check U.S. filing obligations. Form 8898 may be required when residency changes. Federal self-employment or payroll taxes may still apply.
FROM PLANNING TO AN APPROVED DECREE
Residency planning and your exemption application run together. The rate you can claim depends on the approved incentive, its effective terms and your actual facts.
Review citizenship, prior Puerto Rico residence, income sources, unrealized gains, business activities and departure obligations. Decide whether you need an investor decree, an export-services decree or both.
Set a move date, day-count plan and housing budget. For an export business, establish the appropriate entity, registrations and real operations in Puerto Rico, with qualifying services and customers.
Apply through Puerto Rico’s Department of Economic Development and Commerce (DDEC) incentives process with the required documents and fees. Retain proof of filing and respond to requests for further information.
Review the approved activities, effective date, term and conditions with your adviser. Complete acceptance and required payments. Filing alone is not an approved exemption or proof of federal residency.
Claim the applicable treatment on eligible income under the decree. For export services, this is generally the 4% rate on qualifying net business income. For investors, the application-date framework governs. Complete annual filings, contributions and the home purchase requirement where applicable.
Application authority and requirements: Act 60, Sections 2023.01 and 6020.01–6020.04 · DDEC incentives office
HOW EXITGLOBAL HELPS
Bring your departure and Puerto Rico plans into one organized file, so you can see what to do next and where specialist advice is needed.
Use the free Exit Plan to record where you are leaving, your Puerto Rico destination, your timeline, family ties, income and priorities. Keep track of days and a planning budget.
Bring together travel records, housing plans, business details and investment questions. A compiled report organizes your submitted information, missing records and open questions for the next discussion.
A separately agreed written team review adds comments on your prepared file and questions for relevant specialists. Puerto Rico and U.S. tax advice, decree applications and filings need a separate professional engagement.
Prefer a simple reference? Download the free checklist PDF.
CLEAR SCOPE. AN ACCESSIBLE FIRST STEP.
Start your tax exit preparation for free. Bring your facts, records and open questions together before deciding where professional advice would add the most value.
Build your plan for free. Add a compiled report for US$27 or a separately agreed written team review for US$497. Pay for the level of help you choose.
Tax advice, calculations, returns and legal work are separately scoped. The plan and report prepare your information; they do not establish your tax status.
START FREE. CHOOSE HELP WHEN IT ADDS VALUE.
Prepare your position first. Choose a report or written review when you want help taking it further.
Free
For organising the facts, residency questions and next steps behind your tax exit.
No card or account needed to start.
US$27
For bringing your tax exit facts and supporting records into one preparation report.
Preparation service. Professional review is separate.
US$497
For written comments on your prepared facts, evidence and unresolved questions.
Provided under a separately agreed review engagement.
Report and review prices are in US dollars. Tax returns, immigration applications, valuations and complex legal or tax work are outside these preparation offers and are scoped separately. Ask about your situation if you are unsure which option fits.
No. The export-services rate generally applies to eligible net business income under an approved decree. The investor 4% framework applies to qualifying investment income for applications filed from January 1, 2027. Your residency, income source and federal obligations must be assessed separately.
No. The common presence test is at least 183 days in the tax year, but you must also satisfy the tax home and closer connection tests. A decree or property purchase alone does not establish federal bona fide residence.
The Act 60 resident individual investor route generally requires a principal residence purchased from an unrelated seller within two years after obtaining the decree. You must maintain qualifying ownership and provide annual evidence. Renting alone does not meet that decree requirement.
Act 60 resident individual investors generally contribute at least US$10,000 annually: $5,000 to listed child-poverty organizations, $2,500 to another qualifying nonprofit, and $2,500 to the Special Fund for Social Equality. A separate US$5,000 annual-report fee also applies. Older Act 22 decrees can have different conditions.
ExitGlobal helps organize your facts, supporting records and next steps. A separate written review can add team comments. These preparation services do not include government applications, tax filings or a residency determination; specialist work requires a separate engagement.
We help you prepare the facts and questions needed to assess your departure and your position in Puerto Rico. A visa, residence permit or local registration alone does not establish that you qualify for a particular tax treatment. Your former country’s rules, income sources and any applicable treaty also need review.
Start by documenting your circumstances, supporting evidence and unresolved questions. The free plan organises your preparation; the compiled report brings your submitted information together; a separately agreed written review adds team comments. Individual professional advice, filings and any authority determination require the relevant separate process.
The Exit Plan helps you organise your route, priorities, situation and next steps. You can also keep track of days and a planning budget. Starting a plan does not order a report or book a review.
No. Start the planner without either. Save a copy on your device, export it, or create an account when you want to save it there. Save again after making changes.
You can start before choosing a destination. Use the country guides to collect questions, then update your plan as your shortlist changes.
The free planner is a tool you work through yourself. The paid report compiles your submitted answers and documents into a structured preparation file with missing information and open questions identified.
Consider it when you want our team to examine your prepared file and provide written comments under an agreed review engagement. Complex tax calculations, valuations, legal work and filings require a separate scope.
No. Planning and document preparation do not establish tax residency, secure immigration approval or replace a personal professional assessment. Government authorities make their own decisions.
Yes. Begin with what you know. Keep a list of missing records and questions to resolve; you do not need a complete file to start planning.
Rules reviewed September 13, 2026. This is a general overview; your decree, income sources and individual circumstances determine the applicable treatment. Review the enacted amendments alongside the consolidated code.
START YOUR TAX EXIT PLAN
Start free. Put your residency questions, supporting facts and next steps in one place.
Build my free tax exit planNo card or account needed to start.
Edit monthly and annual assumptions, record dated quotes, and see first-year expenses and cash needs.
No email or account needed. Optional topic updates come after your results.
PRACTICAL MOVING GUIDES
Three distinct guides, official sources and free worksheets you can use privately.
An arrival checklist for U.S. citizens moving from the mainland: work, housing, healthcare, travel records and a realistic first-quarter budget.
Understand the three federal residence tests, the special move-year rules and the evidence a mainland mover should keep throughout the year.
Compare Puerto Rico export-services and resident-investor programs, their history, 2026–2027 law changes, annual obligations and practical income examples.
Planning guide · Preparation checklist · Frequently asked questions